Changes to California Health Insurance in 2026
For many residents, the changes to California’s health insurance plans in 2026 represent significant financial adjustments. The expiration of federal subsidies will likely lead to higher premiums for middle-income earners. Meanwhile, new state laws reshape Medi-Cal eligibility and introduce California-funded tax credits for low-income earners. Whether you’re enrolled in Covered California, rely on Medi-Cal or are shopping for a new plan, understanding these legal changes helps avoid unexpected costs.
You don’t need to navigate these complex shifts alone. Health for California provides free, expert guidance to help you. Our licensed agents can calculate your eligibility for state-funded credits. You can find out exactly how the 2026 health insurance changes affect your wallet and secure affordable coverage for your family.
What’s Changing in California Health Insurance for 2026
The American Rescue Plan (ARP) and Inflation Reduction Act (IRA) established the enhanced subsidies from 2021 to 2025. These laws also capped health insurance premiums at 8.5% of household income for everyone, regardless of earnings. Along with the expiration of the subsidy, this cap disappeared starting January 1, 2026. The subsidy cliff returns, meaning households earning more than 400% of the Federal Poverty Level (FPL) may lose federal premium assistance entirely.
While federal support scales back, the state mandate to have coverage remains. The federal tax penalty for not having coverage dropped to $0 during the administration of President Trump. However, California passed its own law, where a lack of coverage can cost at least $950 per adult as a penalty. The state charges whichever amount is higher. You must qualify for a specific hardship exemption to avoid penalties.
Retirees under 65 face the highest risk from the subsidy cliff, as insurance premiums are age-rated. Older adults may pay up to three times more than younger adults. Without the federal income cap, an early retiree earning slightly over the 400% FPL limit can face premiums that consume 20% or more of their fixed income. If you belong to this group, Health for California can help you plan strategically to get the optimal coverage.
Premium Trends and What Californians Should Expect
Base insurance rates rise annually due to medical inflation and increased utilization of health care services. However, Californians may experience steeper increases due to the loss of subsidies. Middle-income families face the hardest hit. Paying the full premium can double or triple their monthly expense overnight.
The Internal Revenue Service (IRS) also imposes stricter reconciliation rules. In 2020, the IRS suspended repayment amounts for excess subsidies entirely, while it capped the payments from 2021 to 2025. Those protections generally end in 2026. This lack of protection means you must report accurate income to avoid receiving subsidies you don’t qualify for. You should also report changes to your income immediately to avoid a surprise tax bill.
The New California State Subsidy Program
Despite the changes, California does not leave residents without options. The new rules on health insurance for 2026 include protections for lower-income residents. The state is providing relief for those who need it most through the California State Subsidy Program. This program replaces the lost federal aid and can prevent residents from dropping coverage due to cost.
The new state credits focus on individuals and families earning between 100% and 165% of the FPL. For eligible enrollees, these state credits lower the monthly premium of a standard Silver plan to $0. You don’t need to apply separately. When you check the 2026 income limits and enter your data during enrollment, the system automatically applies these state credits if you qualify.
Special Considerations for Different Groups
The laws taking effect in 2026 do not affect everyone equally. For instance, in 2024, California waived the asset test for Medi-Cal and looked only at income. Starting January 1, 2026, the state reinstated the asset limit for specific Medi-Cal programs, particularly those for older adults and people with disabilities. Covered individuals can have up to $130,000 in countable assets, such as savings and second properties, without losing eligibility. Your primary home and one vehicle generally remain exempt from this limit.
Effective January 1, 2026, an enrollment freeze applies to undocumented adults aged 19 and older for full-scope Medi-Cal. Deferred Action for Childhood Arrivals (DACA) recipients are no longer eligible for Covered California due to federal changes, similar to other undocumented residents.
How to Prepare for 2026 Changes
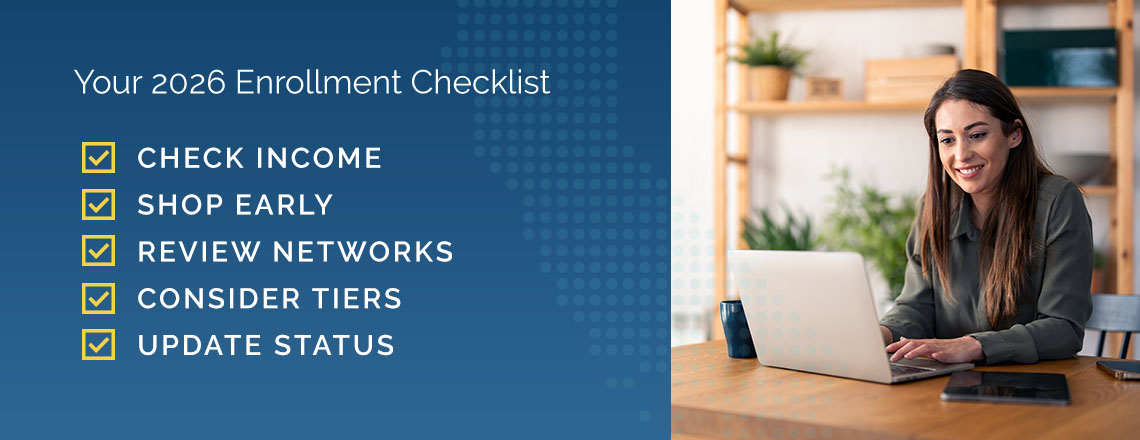
The best way to navigate the California health insurance changes in 2026 is to take action during the open enrollment period. Here are the steps you can take to prepare:
- Check your household income: Your subsidy eligibility depends on your projected 2026 income — not what you earned in 2025. If your income fluctuates, be conservative. Estimate slightly higher and receive a refund at tax time. Overestimating can be safer than underestimating and facing a repayment demand.
- Shop early and compare plans: Don’t let your plan auto-renew without confirming the details.
- Review plan networks: Insurance carriers often change doctor networks in January. Verify your doctor is still covered.
- Consider changing tiers: If you have a Gold plan, your premium might skyrocket. A Silver plan with cost-sharing reductions might offer better value.
- Stay on top of state credits: Ensure your application reflects your current status so you don’t miss out on the new California-specific tax credits.
- Consult a licensed broker: Federal websites may not clearly show California-specific credits or explain asset limit nuances. A licensed agent can navigate both the federal and state rules to find the sweet spot for your coverage.
Common Questions About 2026 Health Insurance Changes
To further help you navigate the 2026 changes, consider these common questions and their answers:
Will Health Insurance Go Up in 2026?
For most people, health insurance premiums can increase. Base rates are rising, but the loss of federal subsidies means the amount you pay out-of-pocket could increase significantly more than the base rate, especially if you earn over 400% of the federal poverty level.
Is There a Penalty for Not Having Health Insurance in 2026?
Yes. California enforces a state Individual Mandate. Unless you qualify for an exemption, you can face a penalty when filing your state taxes if you go without coverage for more than three consecutive months.
Can I Still Get Subsidies if I Make Over $100,000?
It depends on your household size. Under the 2026 rules, the subsidy cliff returns. If your household income exceeds 400% of the FPL, you likely will not qualify for premium assistance.
What Happens if I Forget to Update My Income?
If your income is higher than what’s on file, the IRS may require you to pay back the subsidies you received. Starting in 2026, the repayment caps are tighter, meaning you could owe thousands of dollars for incorrect estimates.
I Have California Public Employees’ Retirement System (CalPERS) Insurance. Do These Changes Affect Me?
Generally, no. CalPERS health plans negotiate their own rates and benefits separately from the Covered California marketplace. CalPERS members still see premium adjustments due to medical inflation. However, they are not subject to the same subsidy cliff rules as individual market consumers.
Get Expert Guidance Today
Navigating the 2026 subsidy changes and new eligibility rules doesn’t have to be stressful. You don’t need to calculate FPLs or decipher complex tax laws on your own. At Health for California, our licensed agents make the process simple — and our services are completely free.
We can help you calculate your new subsidy eligibility, compare state-funded credit options and find a plan that protects your health and your budget. Don’t risk facing the subsidy cliff alone and get a free quote today.