5 Health Insurance Options for California Small Businesses
Posted: June 11, 2024
Last Updated: May 21, 2026
As a small business owner in California, you need to offer competitive health care benefits to attract and retain top talent. But the sheer complexity and cost of available options can feel overwhelming. Between traditional group plans, reimbursement arrangements and alternative models, it’s easy to get stuck in analysis paralysis or settle for a solution that doesn’t fit your budget. You need a guide to make confident decisions that align with your long-term goals.
Each health insurance option has distinct advantages, cost structures and administrative requirements. Your best choice depends on the number of employees, your budget control preference and management bandwidth. The ideal option for a 10-employee business may not be the same as one with 50 employees. Understanding the most common health insurance options for small businesses in California should help.
Key Overview: Small Business Health Insurance Options
Before diving into the details, here’s a quick comparison of your five main options:
| Key Feature | Typical Cost Structure | Best For | |
|---|---|---|---|
| Traditional Small Group Health Plan | Employer-owned group policy | Fixed monthly premiums | Businesses wanting traditional benefits |
| Health Reimbursement Arrangement (HRA) | Tax-free employee reimbursement | Fixed monthly allowance | Businesses wanting budget control and flexibility |
| Professional Employer Organization (PEO) | Co-employment model | Percentage of total payroll | Businesses wanting to outsource administrative tasks |
| Health Care Sharing Ministry (HCSM) | Member sharing of medical bills | Monthly share amount | Faith-based groups with low health risks |
| Defined Contribution | Fixed dollar amount for individual plans | Fixed monthly allowance | Businesses wanting to give employees total choice |
Health Insurance Options for Small Businesses
Choosing among the five common health insurance options comes down to what matters most to you based on your business model and priorities.
1. Traditional Small Group Health Plans
Traditional small group health plans are what most people think of when they hear employer-sponsored health insurance. In California, you can purchase these plans through Covered California for Small Businesses (CCSB), which is similar to the federal Small Business Health Options Program (SHOP). These group policies cover eligible employees and are available to businesses with one to 100 employees. To qualify, you need at least one W-2 employee besides owners or a spouse. You’ll also need a Federal Employer Identification Number (FEIN) and payroll records.
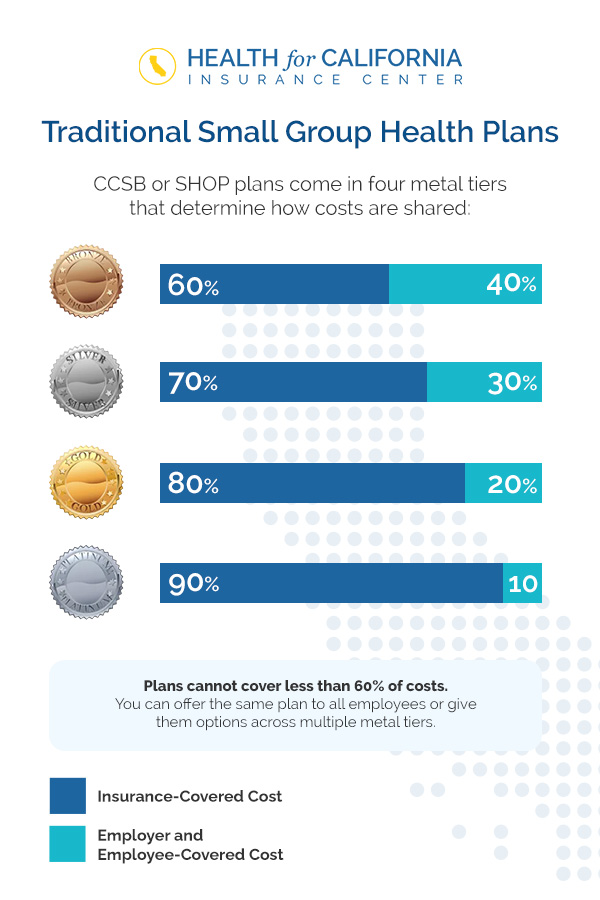
CCSB or SHOP plans come in four metal tiers that determine how costs are shared:
| Metal Tier | Insurance-Covered Cost | Employer and Employee-Covered Cost |
|---|---|---|
| Bronze | 60% | 40% |
| Silver | 70% | 30% |
| Gold | 80% | 20% |
| Platinum | 90% | 10% |
Plans cannot cover less than 60% of costs. You can offer the same plan to all employees or give them options across multiple metal tiers.
Traditional group plans come with network options. Health maintenance organization and preferred provider organization plans are available, which include coverage for preexisting conditions and essential health benefits.
2. HRAs
An HRA is an employer-funded benefit that allows you to reimburse employees tax-free for their medical expenses, including individual health insurance premiums. An HRA is not a group plan. Instead, you set a monthly allowance, and employees choose their own plans from the marketplace.
There are two HRA types for small businesses:
- Qualified Small Employer HRA (QSEHRA): A QSEHRA is for businesses with fewer than 50 full-time employees that don’t offer a group plan. You decide your contribution amount within the IRS’s annual limits. The funds are tax-free, and you only pay for claimed reimbursements — employees need to submit proof of payment.
- Individual Coverage HRA (ICHRA): An ICHRA works similarly to a QSEHRA but is available to employers of any size and has no contribution limits.
Both options give you budget control while letting employees select plans that fit their needs. The trade-off is that employees must have minimum essential coverage to use HRA funds, and the reimbursement amounts may affect their eligibility for premium tax credits on marketplace plans.
3. PEOs
A PEO handles HR functions for you, including payroll, compliance and benefits management. The key concept is co-employment. The PEO becomes the employer of record for tax purposes, which lets your small business access large-group benefits typically reserved for companies with hundreds of employees.
PEOs appeal to owners who want to outsource HR administration. Instead of researching plans, managing enrollment and handling billing, the PEO bundles these services together. You only need to pay the PEO a percentage of your total payroll.
The advantage is simplicity and access to better rates through the PEO’s larger risk pool. The downside is that you give up some control over plan selection and HR decisions. You’re also locked into the PEO’s carrier relationships, so if you’re particular about which insurance companies you work with, this may not be the best fit.
4. HCSMs
HCSMs are membership-based nonprofits where members with shared religious or ethical beliefs contribute monthly to share in each other’s medical bills. However, HCSMs are not really insurance — they don’t guarantee claim payments. They’re not legally required to pay even if they share funds with members who have health care needs. They also usually cap payment requirements.
Most HCSMs operate on faith-based principles and require behavioral commitments, such as promises to avoid smoking, drugs and illegal activity. Coverage decisions are made on a case-by-case basis, and what’s covered can change at any time without notice. The California Department of Insurance warns that most HCSMs don’t comply with the Affordable Care Act (ACA), don’t cover preexisting conditions and don’t cap out-of-pocket costs. The appeal lies in lower monthly costs compared to traditional insurance premiums.
The risks include significant financial exposure if your claims aren’t shared and no legal recourse for denied payments. HCSMs may be worth considering if you’re in good health and seeking a lower-cost alternative. However, they may not be your best option if you have preexisting conditions or need guaranteed coverage.
5. Defined Contribution Health Plans
In a defined contribution health plan, you provide employees a fixed allowance to purchase their own health coverage, rather than offering traditional group health insurance. You set a monthly dollar amount and give employees the freedom to choose a plan that fits their needs. This arrangement offers better budget control without sacrificing health care coverage.
You can implement defined contribution health plans through HRAs or health savings accounts (HSAs). An HSA is a tax-free savings account that employees own and control. Unlike HRAs, which employers fund and own, HSA funds belong entirely to the employee and stay with them even if they leave your company or switch health plans. Employees can contribute pretax dollars to their HSAs, and you can contribute as well if you choose. The funds grow tax-free through interest and investments, and withdrawals for qualified medical expenses are tax-free.
Do Small Businesses Have to Offer Health Insurance in California?
Under the ACA, the employer mandate to offer health insurance only applies to businesses with 50 or more full-time equivalent employees. However, many small businesses choose to do so anyway to attract and retain talent in competitive job markets — especially when 89% of employees prefer to get employer-sponsored coverage. About half of U.S. adults with comprehensive coverage also work in a small business or are self-employed. The decision ultimately depends on your budget, your industry’s competitive landscape and your company’s values around employee benefits.
If you choose to offer coverage, working with a knowledgeable agent makes the process easier. Navigating CCSB can be confusing or time-consuming, considering the research you need to perform on your own. With Health for California, you can find the optimal health insurance for your small business in a few minutes.
How to Select the Right Health Insurance
To adequately evaluate the types of health insurance for small businesses, consider these factors:
- Budget: How much can you afford to contribute monthly? Traditional group plans and PEOs come with fixed premiums that can fluctuate annually. HRAs and defined contribution models let you set a fixed allowance that gives you more spending control.
- Flexibility: Do you want to control which plan your employees have access to, or do you want them to have full choice? Traditional group plans limit employees to the options you select. However, by enrolling through CCSB or California Choice, you can give your employees multiple options to choose from, while having a defined budget. Alternatively, HRAs and defined contribution plans let employees shop the individual marketplace. This difference matters if your workforce has diverse needs — some may want high-deductible plans with HSAs, while others may be willing to pay higher premiums for lower deductibles. Group plans also have the potential for richer benefits.
- Administrative capacity: How much time can you dedicate to managing the plan? If you have limited bandwidth, a PEO can simplify the process. If you’re comfortable with more hands-on management, traditional group plans or HRAs give you direct control.
Frequently Asked Questions
Here are answers to some of the most common questions small business owners ask about health insurance.
Can I Write Off My Health Insurance if I Own My Business?
Yes, business owners can write off their insurance costs through the Self-Employed Health Insurance Deduction. Sole proprietors, partners and S-corp shareholders can generally deduct premiums paid for themselves, their spouse and dependents. This deduction is reported on Schedule 1 of Form 1040 and can include medical, dental and vision insurance, as well as qualified long-term care insurance.
The deduction is not allowed for any month you were eligible for an employer-subsidized health plan — whether through your own employer-sponsored plan, your spouse’s plan, your dependent’s plan or your child under 26’s employer plan. Eligibility alone disqualifies you, even if you didn’t enroll.
For the deduction to apply, the insurance plan must be established under your business:
- If you’re self-employed, the policy can be in your business name or your individual name.
- If you’re a partner, the policy must be in the partnership or partner name, paid or reimbursed by the partnership, and reported as guaranteed payments.
- For S-corp shareholders, the policy must be in the corporation’s or shareholder’s name, paid or reimbursed by the S-corp and reported as W-2 wages.
Can I Use My LLC to Get Health Insurance?
You may be able to use your limited liability company (LLC) to get insurance, depending on how many employees you have. If you’re a single-member LLC with no employees, you’re considered self-employed for health insurance purposes. You would purchase an individual or family plan from the marketplace, not a group plan. Self-employed individuals with no employees don’t qualify for SHOP group coverage. If your LLC has at least one W-2 employee besides the owner or spouse, you may then qualify for a small group health plan.
Group plans come with different benefits, protections and potentially lower costs due to risk pooling. If you’re planning to hire employees soon, it may be worth waiting to set up group coverage rather than purchasing individual plans and switching later. A Health for California agent can help you review your options carefully and choose the optimal health insurance.
What Is the Small Business Health Care Tax Credit?
The Small Business Health Care Tax Credit helps the smallest businesses better afford coverage. To qualify, you must meet these requirements:
- You need fewer than 25 full-time equivalent employees.
- Your average employee salary must be about $65,000 per year or less.
- You must pay at least 50% of the full-time employees’ premium costs.
- You must offer coverage through a SHOP marketplace like CCSB.
The credit can be worth up to 50% of your contribution if you’re a for-profit business and up to 35% if you’re a tax-exempt organization. The credit is highest for companies with fewer than 10 employees and average employee salaries of $27,000 or less. The smaller your business, the bigger the credit.
This credit is only available if you enroll in a SHOP plan. If you choose an HRA, PEO or other alternative, you won’t qualify. The tax credit can make traditional group coverage significantly more affordable for very small businesses, so it’s worth calculating your potential savings before deciding which route to take.
What Is the Penalty for Having No Health Insurance in California in 2026?
California’s minimum penalty for not having coverage is $950 per adult and $450 per dependent child under 18. A family of four without coverage for the entire year would face a penalty of at least $2,800. Your actual penalty may be higher depending on your household income and circumstances. The California Franchise Tax Board administers the penalty, which applies to any month you go without coverage. Exemptions are available for financial hardship, affordability issues and religious conscience reasons.
Find an Insurance That Fits Your Needs With Health for California
Navigating health insurance options doesn’t have to be complicated. Health for California simplifies what is normally a difficult, time-consuming process by connecting you with the right coverage for your small business needs. Whether you’re exploring traditional group plans, HRAs or other alternatives, our team makes it easy to compare options and find a solution that fits your budget and goals.
Our streamlined application process is designed specifically for California small businesses like yours. If you’re ready to find health insurance that works for your team, get your free quote today.