Covered California Plans: Metallic Plan Benefits
Find Bronze, Silver, Gold and Platinum Obama Care Plans and Prices
When the Affordable Care Act (ACA) became law, health insurance plans were repackaged, and categorized into 4 metal tiers: Bronze, Silver, Gold and Platinum. Covered California took this a step further and streamlined all the plans they offered on-exchange, so they became a real “apples to apples” comparison.
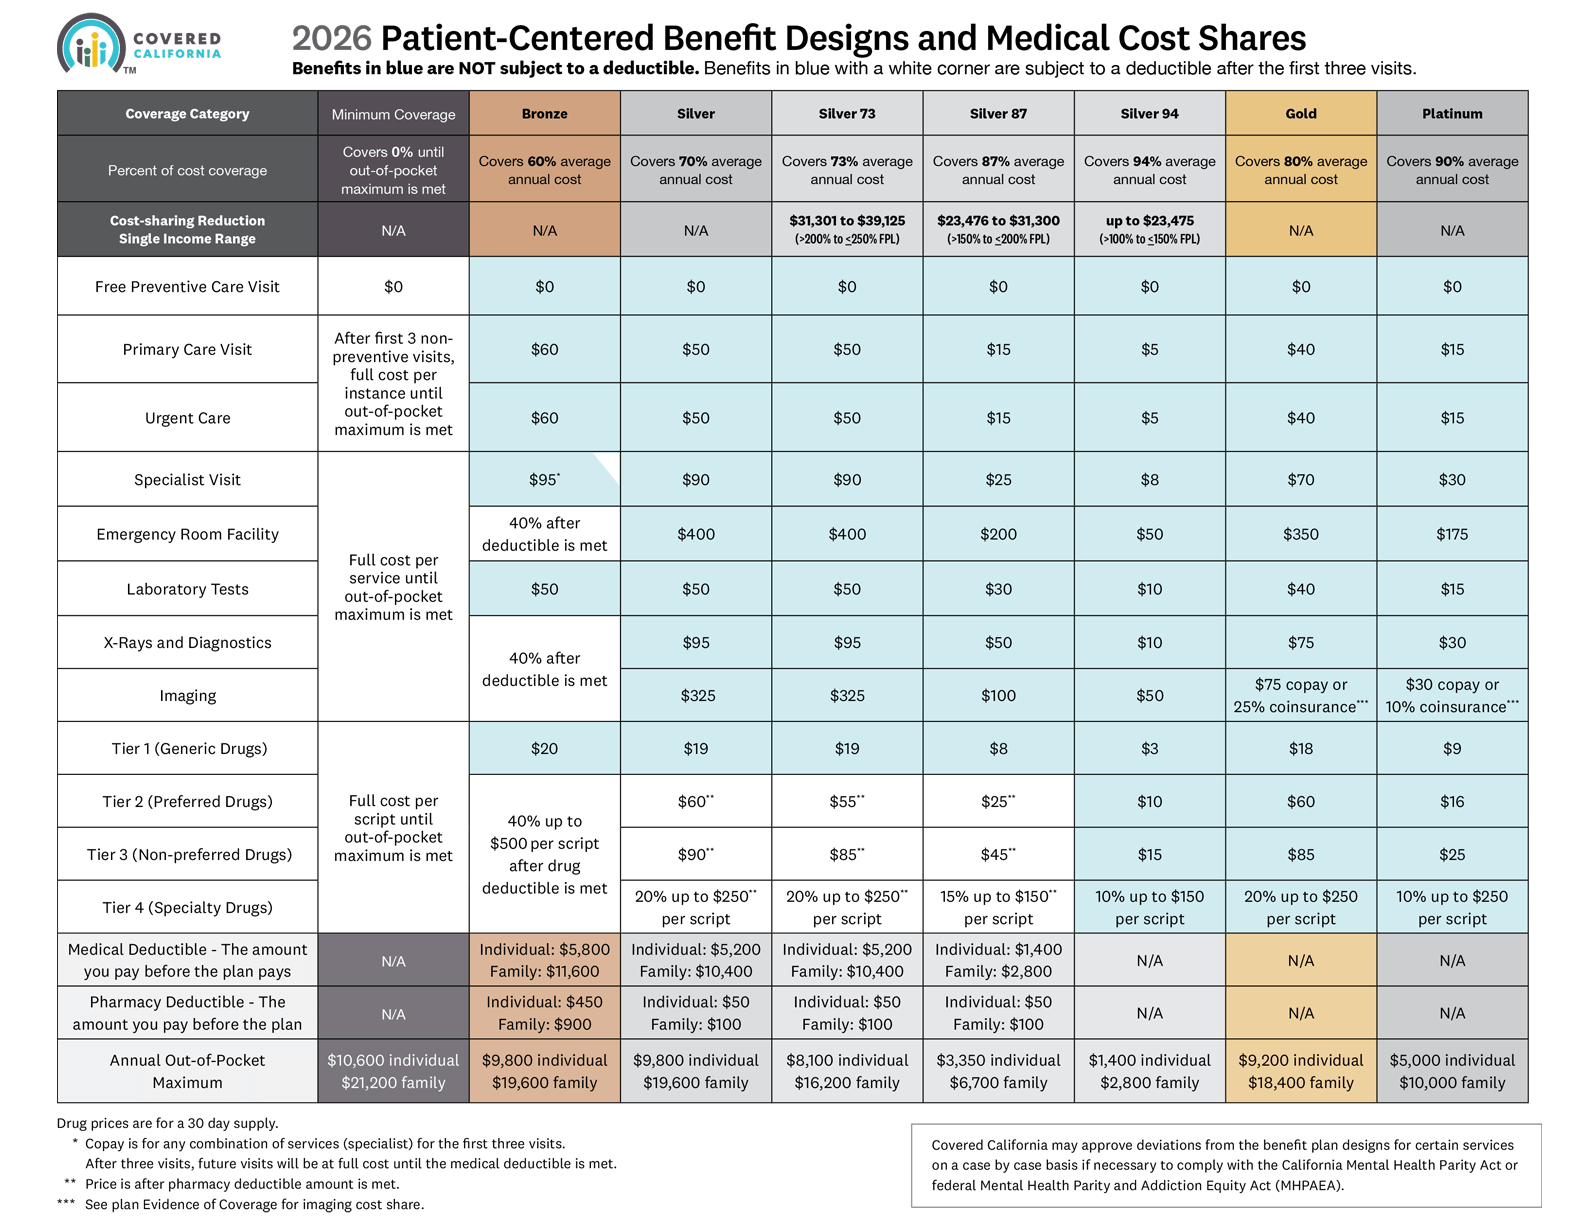
The silver tier is the most popular, so using it as an example, if you were looking at all of the Silver 70 plans on the Covered California marketplace, there would be no plan benefit differences. You would only have to decide which carrier you want, and whether you want an HMO, EPO, or PPO. These acronyms represent the type of network you would have access to and essentially which doctors, and hospitals accept your insurance.
The metal plan categories help identify how much you would pay for estimated average medical costs, compared to how much the insurance company pays. It has nothing to do with the quality of care given.
All plans include the 10 Essential Health Benefits that are required to be covered by law.
- Ambulatory patient services (outpatient)
- Emergency Services
- Hospitalization
- Maternity and newborn care
- Mental health and substance use disorder services (including behavior health)
- Prescription drugs
- Rehabilitative and habilitative services and devices
- Laboratory services
- Preventive and wellness services and chronic disease management
- Pediatric services, including some dental and vision care (included for children only)
Below you will see a summary of the 4 metal tiers along with the minimum coverage plan.
Best For:
A healthy individual/family that does not have medical conditions, but wants insurance just in case something major happens
Features:
- Free preventative care
- Primary Care Physician (PCP) visits are a fixed copay (dollar amount) before deductible is reached.
- High deductible
- Out-of-pocket maximum limit; which is the most you would pay in a calendar year if the worst happened.
Bronze HDHP (High Deductible Health Plan) 60 Plan:
Best For:
A healthy individual/family that wants to take advantage of tax savings, and plans on putting money into a special bank account called a Health Savings Account. This money can be used for medical expenses and the money roles over from year to year.
This is considered a major medical health plan so it would be good for someone who wants catastrophic coverage. In addition, those that prefer alternative medicine find this an attractive option as many of the services can be paid for with money from an HSA. Check the IRS publication 502 as to what medical services are eligible.
Features:
- Free preventative care
- High deductible
- Out-of-pocket maximum limit (which is the most you would pay in a calendar year if the worst happened). The out-of-pocket maximum would be quite a bit lower than the standard Bronze 60 plan above.
Best For:
A healthy individual/family who wants an affordable middle of the road Obama Care plan that offers reasonable copays for common services such as office visits, lab work, and generic drugs.
Features:
- Free preventative care
- Common services such as doctor visits, lab work, generic drugs, and emergency room visits for a set copay (dollar) amount without having to meet your deductible first.
- High deductible for major services such as hospitalization.
- Out-of-pocket maximum limit; which is the most you would pay in a calendar year if the worst happened.
Best For:
A healthy individual/family that frequently uses medical services and/or wants an Obama Care plan without a deductible
Features:
- Free preventative care
- Reduced prices for medical services in the form of copays (fixed dollar amounts) or coinsurance (a percentage of the medical costs) right from the start of your plan
- No deductible
- Out-of-pocket maximum limit; which is the most you would pay in a calendar year if the worst happened.
Best For:
Individuals who frequently uses medical services and/or want the best Obama Care plan available with the least out of pocket costs.
Features:
- Free preventative care.
- The lowest costs for medical services in the form of copays (fixed dollar amounts) or coinsurance (a percentage of the medical costs) right from the start of your plan.
- No deductible.
- The lowest out-of-pocket maximum limit available of all the Obama Care plans offered which is the most you would pay in a calendar year if the worst happened. (Exception: Some lower income people may qualify for an Enhanced Silver Plan which may have an even lower OOP Max.)
Best For:
Children and young adults who are very healthy and don’t qualify for premium assistance, and whose main concern is affordability for the monthly premium.
Important to Note:
Government assistance (subsidies) cannot be applied in reducing the premiums for this plan. It is available only to those who are under 30 years old.
Features:
- Free preventative care.
- First 3 office visits per year are free (for Primary Care Physician, Urgent Care or Mental Health Therapy visits).
- Highest deductible of all the Obama Care plans offered.
- Highest out-of-pocket maximum limit of all the Obama Care plans (which is the most you would pay in a calendar year if the worst happened).
